
Buy now, pay later installment (BNPL) plans help you pay for large purchases in manageable chunks. You're charged a small fee to break the payments down into installments.
Many credit cards offer them, allowing you to avoid typical purchase interest fees. This helps you save money on credit card interest and still be able to afford big-ticket necessities.
Here's our guide on how buy now, pay later credit cards work in Canada – along with a few credit cards that offer this financing.
Key Takeaways
- Buy now, pay later plans split a large purchase into more manageable chunks.
- You'll be charged a fee paying later, but it will usually be less than paying purchase interest.
- Buy now, pay later is offered by both credit cards and other fintechs.
Never miss an amazing deal again + get our bonus 250+ page eBook for FREE. Join 50,000 other Canadians who receive our weekly newsletter – learn more.
What is a buy now, pay later plan or credit card installment plan?
A buy now, pay later – or BNPL – plan is a financing option to make a purchase now and pay for it over time using installments. BNPL can refer to a credit card installment plan or a dedicated payment service like Klarna or Afterpay. Retailers may also offer their own BNPL plans.
While you have many options, buy now, pay later plans fundamentally work the same way:
You make a purchase and then choose to pay for it over a longer period – often 3, 6, or 12 months of equal payments. You typically pay a small fee for this service.
For example, instead of charging a $900 television to your credit card and racking up a balance that incurs mammoth interest charges until you pay it off, your card might be charged $300 every 3 months until the full payment is covered.
This way, your credit card balance remains low, and you have a chance to pay off the smaller installment before interest charges kick in.
How do buy now, pay later credit card plans work?
To set up a plan with a credit card, you'll need to log in to your online account. From there, the steps vary depending on your card issuer.
In most cases, you'll find the statement item that you want to convert to installments and select "convert to installments," "buy now, pay later," or something similar. You may also be able to apply an installment plan to the entire card balance.
From here, you'll be presented with various term options and see what it will cost to get a plan – the installment fee plus your monthly payment.
Important note: The installments will be added to your minimum monthly payment, so you must make sure you can pay them every month.
What do buy now, pay later plans cost?
Because companies are getting the sum of their money later, you'll have to pay fees for the convenience. These include:
- Initial fees for setting up the plan
- A percentage of the purchase amount, either on the total or the monthly charge
The fees are all generally pretty straightforward, so there are no hidden costs that will surprise you in the end.
Is buy now, pay later interest-free?
Most short-term buy now, pay later plans are attractive because they don't charge interest – instead, they charge a small set monthly fee, which you can avoid if you pay off the plan early.
That said, read the terms and conditions carefully, since longer-term plans might charge interest.
Pros and cons of using a credit card installment plan
Using a buy now, pay later program unlocks access to larger purchases without crippling interest rates. Still, you should also consider the potential problems that may arise.
Here's a quick rundown of the pros and cons of using buy now, pay later.
Pros:
- Can purchase big-ticket items that you don't have cash for immediately
- Allows for budgeting without breaking the bank
- Lower interest rates than credit cards (sometimes with 0% financing)
- No application required
Cons:
- Costs more in total than buying outright
- Temptation to spend more than you can budget for
- Steep late/missed payment fees
- Risk of going into overdraft
Buy now, pay later credit card issuers
Here are the details on the issuers that offer credit card installment plans and how much they charge. For our example, we charged $1,000 to a BNPL program with installments paid out over 12 months.
Please note that these issuers may charge you more or less, depending on your credit score and other factors.
| Issuer | Fees | Effective annual rate* |
|---|---|---|
| American Express | Variable monthly fee | 11.3% – 20.82% |
| MBNA | Variable total fee: 4 – 8 % | 10.11% – 13.71% |
| Scotiabank | No fee; monthly interest rate | 5.99% – 7.99% |
| CIBC | Initial setup fee of 2% Variable monthly interest rate | 10.91% – 13.85% |
*Because some BNPL plans charge a fee instead of interest, we've calculated the effective annual rate so you can compare this to annual interest rates.
1. American Express Plan It
Terms available: 3, 6, 12 months
Minimum amount to participate in BNPL: $100
Exclusions: Not available in Quebec, Prince Edward Island, Nova Scotia, or Nunavut
Let's start with American Express, which runs Plan It.
There isn't a set fee to use it – it all varies based on where you live and how much you put on your plan.
Here's how your Plan It setup might look:
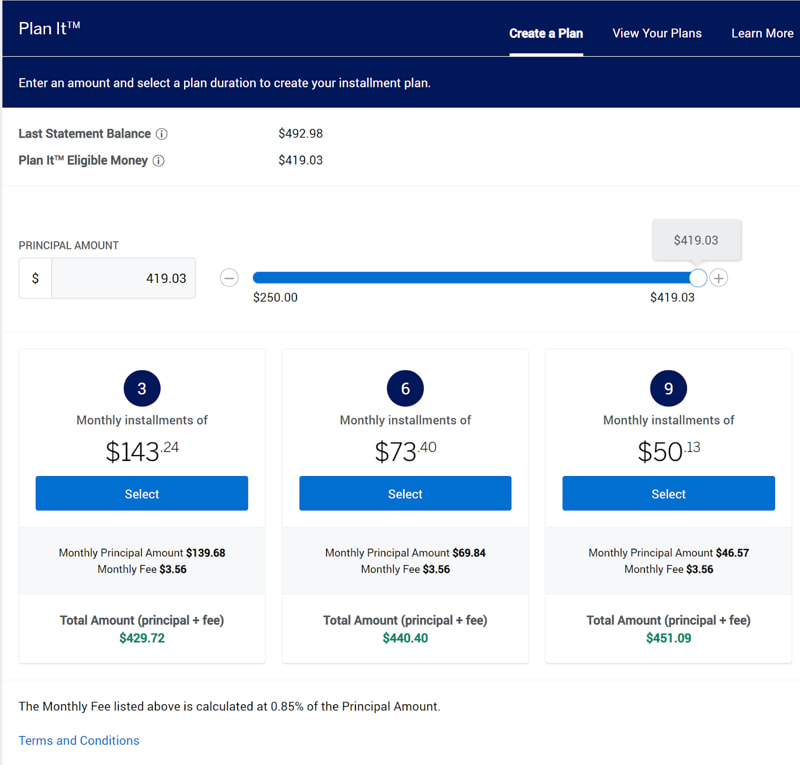
To figure out your total fee, multiply your balance by the installment fee percentage, then by the number of months. Add that fee to your original balance, then divide by the number of months to get your monthly installment.
Amex lists a few different rates in its cardmember agreements, but for our example, we'll use the 0.85% shown above. Assume you want to finance a $1,000 purchase with Plan It.
$1,000 x 0.85% x 12 = $102
If you activate Amex Plan It on the $1,000 loan, your total fee is $102. This brings your purchase to a grand total of $1,102. Divide this by 12 to get your monthly installment – $91.83.
$1,102 / 12 = $91.83
What does this mean for your annual interest rate?
If you repay the $1,000 in 12 equal chunks, the amount you owe drops by the same amount every month, starting at the full $1,000 and ending at just one installment's worth ($1,000 / 12 = $83.33).
This means your average monthly balance would be $541.67, and your effective annual rate would be 18.83%
$102 / $541.67 = 18.83%
Fortunately, you won't need to do all this math. Amex breaks down the effective annual interest rate for each of its monthly rates in the terms and conditions.
| Monthly Installment Fee | Effective Annual Rate |
|---|---|
| 0.51% | 11.30% |
| 0.85% | 18.83% |
| 0.90% | 19.94% |
| 0.94% | 20.82% |
Amex typically charges 21.99% in purchase interest. So no matter which BNPL fee you pay, you come out on top – but it makes a much bigger difference if your fee is lower.
American Express credit cards
Amex Plan It is available on most personal Amex credit cards, except Amex charge cards.
Here are some of the best Amex cards that can use Amex Plan It:
American Express Cobalt® Card Marriott Bonvoy® American Express®* Card SimplyCash® Preferred Card from American Express
2. MBNA Payment Plans
Terms available: 6, 12, 18 months
Minimum amount to participate in BNPL: $100
Exclusions: Not available in Quebec
MBNA has Payment Plans, which charge a fee based on the total purchase amount and the program term length you pick. Your term options and their percentage fees are:
- 6 months – 4%
- 12 months – 6%
- 18 months – 8%
To calculate your total fee, simply multiply your purchase amount by the fee rate for your installment term.
Then, to get your total monthly payment, add this fee to your initial purchase amount and divide by the term length (6, 12, or 18 months).
So, for our $1,000 purchase spread over 12 months, it's:
([$1,000 x 6%] + $1,000) / 12 = $88.33
Over the course of a year, you've paid $60 in fees. MBNA doesn't charge interest on Payment Plans — but expressed as an effective annual rate, that fee works out to 11.08%.
Remember, we determined in the previous that our average balance is $541.67. Therefore:
$60 / $541.67 = 11.08%
This is much lower than a typical purchase interest rate of 21.99%, which you would pay if you made the $1,000 purchase on your credit card and didn't pay it off with your usual monthly payment.
Since the term length also affects your effective annual rate, we've done the math for you:
| Total Fee | Effective Annual Rate |
|---|---|
| 4% on 6 months | 13.71% |
| 6% on 12 months | 11.08% |
| 8% on 18 months | 10.11% |
MBNA credit cards
All MBNA credit cards are eligible except for cards with standard interest rates less than 12.99% (like the
These are MBNA's best cards:
3. Scotia SelectPay
Terms available: 3, 6, 12 months
Minimum amount to participate in BNPL: $100
Exclusions: Not available in Quebec
Scotia SelectPay offers installment plans on select Scotiabank credit cards. Unlike MBNA and Amex, there's no installment plan fee – instead, you pay regular interest.
You can choose from terms of 3, 6, or 12 months, each with a different interest rate.
- 3 months – 5.99%
- 6 months – 6.99%
- 12 months – 7.99%
Using our typical example of $1,000 for 12 months, the total interest is just about $44. The monthly payment ends up at just about $87, which matches the annual interest rate of about 8%.
Scotiabank credit cards
The list of Scotiabank credit cards eligible for SelectPay is impressive, but it doesn't include all Scotia cards.
Here are the best eligible Scotiabank credit cards:
Scotia Momentum Visa Infinite + Card Scotiabank Passport® Visa Infinite +* Card Scotia Momentum Visa Card
4. CIBC Pace It
Terms available: 6, 12, 24 months
Minimum amount to participate in BNPL: $100
Exclusions: Not available in Quebec
The last major issuer that offers installment plans is CIBC, with its Pace It program.
Pace It is a little more complicated than the other plans. First, the easy part. You'll be charged a 1-time fee of 2% of the purchase amount.
Then, every month you'll be charged interest on the remaining balance. And the interest rate you pay depends on the length of your payment plan.
- 6 months – 6.99%
- 12 months – 7.99%
- 24 months – 8.99%
Calculating the exact amount you'll have to pay can be tricky, but CIBC has made it easier with the CIBC Pace It installment calculator.
For our $1,000, 12-month example, you'll pay a 1-time fee of $20. Including interest, your monthly payment is $86.98, and in total, you'll pay $1,063.81 on your purchase. Because you're paying both a setup fee and interest, that works out to an effective annual rate of about 11.64%.
You'd save $59.27 compared to charging the entire purchase to a credit card that has a 21.99% interest rate.
CIBC credit cards
CIBC Pace It is only available on select credit cards. Here are some of the better ones:
Alternatives to buy now, pay later credit cards in Canada
There are several alternatives to buy now, pay later plans, including:
Low-interest credit cards
Most credit cards have a typical interest rate of around 20%, which is obviously very high. But there are many credit cards with standard purchase rates of 13% or lower.
Most of them don't offer rewards, so they're completely focused on saving money through the lower rates – making them excellent alternatives to buy now, pay later plans.
Here are some of the best low-interest credit cards in Canada.
And here are their standard interest rates on new purchases:
- MBNA True Line Mastercard: 12.99%
- MBNA True Line Gold Mastercard: 10.99%
- RBC Visa Classic Low Rate Option: 12.99%
Personal loans
Personal loans are another way to help with larger purchases. You'll borrow a set amount you can use for anything you like and have stable monthly payments over a pre-set period of time.
One option to find a loan is with LoanConnect. They're essentially a loan search engine and will help you find the best personal loan for you.
LoanConnect
Lines of credit
You can also look into getting a line of credit, which lets you take out as much or as little of the issued credit as you need. Then, you only pay back what you've actually borrowed.
In some cases, the minimum payment you need to make just pays the interest. But try to pay as much as you can – if you just pay the interest, you'll be paying the bank back forever.
Buy now, pay later services
If you don't have a credit card that qualifies for a specific BNPL plan, don't worry, you can still access an installment payment plan through a different service.
These may charge higher fees than a bank, but Canadians can access installment plans through these service providers:
- Afterpay: Your purchases from supported brands are split into 4 interest-free payments over 6 weeks. If you miss payments, you're charged interest and fees.
- Klarna: Split your purchase into 4 interest-free payments and don't pay any fees unless you miss payments.
- Affirm (formerly PayBright): Choose a flexible payment plan of 4 payments or monthly payments. No interest is charged on the shorter Affirm Pay in 4 plan (1 payment every 2 weeks – 4 in total), but interest rates vary for the extended monthly payment plans. Interest ranges from 0% to 32%, so read the terms carefully.
- Sezzle: Break your purchase into smaller payments, but be prepared to pay a service fee of up to 7.49% on top of interest.
FAQ
Which credit cards allow buy now, pay later?
Most of the major credit card issuers, including Amex, MBNA, Scotiabank, and CIBC offer buy now, pay later plans in Canada. If you don't know whether your card has this payment option, check your card's terms and conditions or contact customer service.
What is the easiest buy now, pay later to get approved for?
Buy now, pay later program approval depends more on your credit score than the card issuer's requirements. You'll find it easier to get approved with a better score and if you have been able to stay well below your credit limit.
Can you do buy now, pay later with a credit card?
Yes – more and more credit cards offer a buy now, pay later repayment option. Some issuers even let you set up the plan before making a big purchase, while others let you choose purchases you've already charged to the card.
Are there credit card installment plans in Canada?
Yes. American Express offers its popular Plan It program, MBNA's is called Payment Plans, Scotiabank uses Scotia SelectPay, and CIBC has Pace It. These are all credit card installment plans with some of the biggest credit card issuers in Canada.
What is Afterpay Canada?
Afterpay is a buy now, pay later platform that lets you split purchases from partner brands into 4 interest-free payments over 6 weeks. You'll need an account and the app to get started, and you must make purchases through the app to split your payments.
Is the Klarna credit card available in Canada?
Klarna's credit card is not available in Canada, but its buy now, pay later program is available to Canadians through many major retailers. Canadians can pay with Klarna when shopping online at Amazon, Walmart, Costco, Simons, Wayfair, and more. Canadians can also download the Klarna app.
creditcardGenius is the only tool that compares 126+ features of 250 Canadian credit cards using math-based ratings and rankings that respond to your needs, instantly. Take our quiz and see which of Canada's 250 cards is for you.
 GC:


Comments
Leave a comment
Required fields are marked with *. Your email address will not be published.
Showing 4 comments